
Investing > Learn > 2027 Retirement Limits: 401(k), IRA, Catch-Up and HSA
Investing · Retirement Accounts
Your 401(k), IRA and HSA each get their own 2027 ceiling — here’s what’s official, what’s still projected, and how to plan around both.
Sundas Tahir, Founder & CEO, FinWiser.
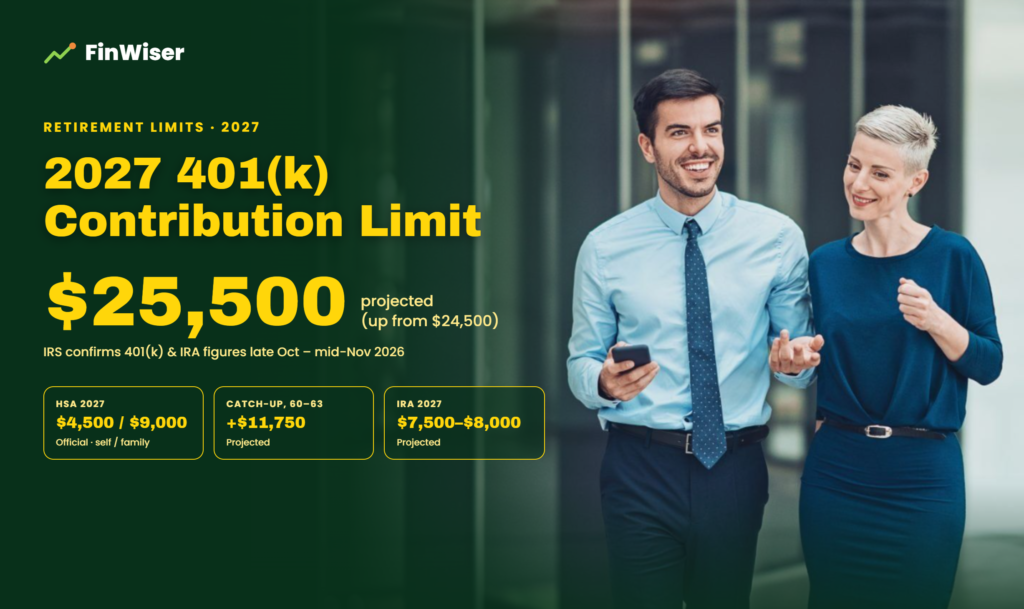
The 2027 401k contribution limit is the single number most savers will check before January, and right now it sits in an odd spot. The IRS hasn’t published it yet, but the inflation math behind it is nearly finished, so the range is already narrow. Meanwhile, the 2027 HSA limits are fully official.
This guide lays out every 2027 ceiling side by side: the 401(k), the IRA, the catch-up tiers and the HSA. There is no single “correct” account here. The right mix depends on your income, your employer’s plan and whether you want to keep interest out of your portfolio.
Don’t wait for the IRS press release to act. Set your 401(k) contribution as a percentage of pay, capture the full employer match first, and only chase the max once your emergency fund is solid. Raising your percentage by a point or two in January matters far more than whether the 2027 401k contribution limit ends at $25,000 or $25,500.
What Is a 401(k) and How Does It Work?
A 401(k) is a retirement account your employer sets up. You choose a percentage of each paycheck, and payroll moves it into the account before the money ever reaches your bank. The name comes from the section of the U.S. tax code that created it.
Inside the account, your money is invested in a menu of funds the plan offers, usually stock funds, bond funds and target-date funds. A traditional 401(k) lowers your taxable income today, and you pay tax when you withdraw in retirement. A Roth 401(k) flips that: you pay tax now, and qualified withdrawals later are tax-free.
Many employers add a “match,” such as 50 cents for every dollar you put in, up to 6% of your salary. That matched money may come with vesting rules, meaning you earn full ownership of it over a few years of service. Your own contributions are always 100% yours.
Because the tax break is valuable, the IRS caps how much you can put in each year. When people talk about the 2027 401k contribution limit, they mean that cap on your own paycheck deferrals for next year. It rises with inflation most years, usually in $500 steps.
Good News: You Don’t Have to Choose
The 401(k), the IRA and the HSA each have their own separate ceiling. Filling one doesn’t reduce your room in the others. If you have a workplace plan, an earned income and an HSA-eligible health plan, you can contribute to all three in the same year.
Maxing out your 401(k) at work also has no effect on whether you can open or fund an IRA on your own. The real question isn’t which account to pick. It’s the order in which you fund them, which we cover in the recommendations below.
The 2027 401k Contribution Limit at a Glance
Here is how the three accounts compare across the same seven criteria. Projected figures come from Milliman’s September 2026 forecast; confirmed figures come from the IRS.
| Criteria | 401(k) | IRA (Traditional or Roth) | HSA |
|---|---|---|---|
| 2026 limit | $24,500 | $7,500 | $4,400 self / $8,750 family |
| 2027 limit | $25,500 projected ($25,000 if September inflation is nearly flat) | $7,500–$8,000 projected | $4,500 self / $9,000 family |
| 2027 status | Projected — IRS notice expected late Oct to mid-Nov | Projected — same IRS notice | Official (Rev. Proc. 2026-24) |
| Catch-up | 50+: $8,500 projected; ages 60–63: $11,750 projected | 50+: $1,100 in 2026, indexed in $100 steps | 55+: $1,000 (not indexed) |
| Who funds it | You plus your employer | You only | You plus your employer |
| Tax break | Pre-tax or Roth | Deductible or Roth | Deductible in, tax-free growth, tax-free medical withdrawals |
| Income limits | None to contribute | Roth and deduction phase-outs apply | None, but you need a qualifying health plan |
Criteria-by-Criteria Breakdown
The base limit for each account
For 2026, the IRS set the 401(k) employee limit at $24,500 and the IRA limit at $7,500. For 2027, Milliman’s latest forecast puts the 401(k) at $25,500, a $1,000 jump. If September prices barely move, it lands at $25,000 instead.
IRA forecasts are less settled, with credible estimates split between staying at $7,500 and rising to $8,000. The HSA is the only one with no guesswork: IRS Revenue Procedure 2026-24 sets it at $4,500 for self-only coverage and $9,000 for family coverage.
How the 2027 401k contribution limit gets set
The IRS doesn’t pick a number. It runs a formula tied to the Consumer Price Index (CPI), then rounds down to a $500 step. The last input, September’s CPI, is released on October 14, 2026, which effectively locks the answer weeks before the official notice.
You don’t need to wait for that notice to plan. Most payroll systems let you pick a percentage, and many stop your deferrals automatically once you hit the cap. If you prefer a fixed dollar amount, divide $25,000 by your number of pay periods for now, then top up in January if the IRS confirms the higher figure.
Planning to the lower number protects you from over-contributing. Excess deferrals have to be corrected by April 15 of the following year, or the same dollars can end up taxed twice.
Catch-up contributions
A catch-up contribution is extra room for older savers. In a 401(k), workers 50 and up are projected to get $8,500 on top of the base in 2027, while ages 60 through 63 get a larger “super catch-up,” projected at $11,750. Stacked on the base limit, that could mean $37,250 in total for someone who is 61.
One rule changed in 2026. If your prior-year Social Security wages from that employer topped $150,000, your 401(k) catch-ups must go in as Roth money. The threshold is indexed, so it can rise in $5,000 steps. IRA catch-ups were $1,100 in 2026, and HSA savers 55 and older keep a flat $1,000 extra.
Who puts money in
Only the 401(k) and HSA accept employer money. Your employer’s match doesn’t count against the 2027 401k contribution limit, which applies only to what you defer from your own pay; a separate combined cap is projected to rise from $72,000 to $75,000. An IRA, by contrast, is funded only by you, though anyone with earned income can open one.
Tax treatment
All three cut your tax bill, just at different moments. Every dollar you defer into a traditional 401(k) lowers that year’s taxable income. The HSA is the standout, since it’s the only account where money goes in untaxed, grows untaxed and comes out untaxed for medical bills. A Roth IRA or Roth 401(k) skips the upfront deduction in exchange for tax-free withdrawals in retirement.
Income limits and eligibility
The 401(k) has no income cutoff for contributing. Roth IRAs do: in 2026, the single filer phase-out ran from $153,000 to $168,000. HSAs have no income test, but you must be covered by a high-deductible health plan, which for 2027 means a deductible of at least $1,750 for self-only coverage or $3,500 for a family.
By the Numbers: Few People Actually Max Out
Here’s the reality check. According to Vanguard’s How America Saves 2026 report, only 14% of participants hit the 2025 maximum of $23,500. The average total savings rate, employee plus employer, was 12.1%.
So for most readers, the 2027 401k contribution limit is a ceiling, not a target. The bigger win usually comes from nudging your savings rate up each year, especially through auto-escalation features that raise your percentage on a schedule.
That doesn’t make the new numbers irrelevant. If you’re one of the people already near the cap, the extra $1,000 of room is worth claiming, and the catch-up tiers add meaningful space in your 50s and early 60s.
A Halal-Aware Note on These Accounts
None of these accounts is inherently interest-based. A 401(k), IRA or HSA is just a tax wrapper, so the riba question depends on what sits inside. Bond funds, stable-value funds and money market defaults all earn interest, and HSAs often park uninvested cash in an interest-paying fund.
A halal-conscious saver can still use the full 2027 401k contribution limit and every other ceiling here. Check whether your plan offers a Shariah-screened fund or a self-directed brokerage window, and screen the menu with a tool like Zoya. Avoid 401(k) loans, since they charge interest even though it’s paid back to you; scholars differ on that point. Retirement balances may also carry zakat obligations.
5 providers to know
- Saturna Capital (Amana Funds) — the oldest U.S. family of Shariah-screened mutual funds, now also offered as ETFs, and available in some workplace plans.
- Wahed — a halal robo-advisor with IRA accounts and 401(k) rollovers into screened portfolios.
- Zoya — a screening app for checking whether the stocks and funds on your plan menu pass Shariah criteria.
- Fidelity HSA — an HSA with no account fees and a wide investment menu, so you can choose what your cash goes into.
- Vanguard — a low-cost IRA provider; its standard index funds aren’t Shariah-screened, so halal-conscious savers should pick funds carefully.
Pros and Cons of Each Account
Where the 401(k) Wins
- Biggest room by far. The 2027 401k contribution limit is more than three times the IRA ceiling.
- Free employer money. A match is an instant return you can’t get anywhere else.
- Autopilot saving. Payroll deductions happen before you can spend the money.
- Drawback: a limited menu. You’re stuck with your employer’s funds, which may not include a halal option.
Where the IRA Wins
- Full investment control. You choose the provider, so a fully screened portfolio is easy to build.
- Works without an employer. Freelancers and gig workers can open one on their own.
- Drawback: small limit. Even at $8,000, it’s less than a third of the 2027 401k contribution limit, so it can’t carry your whole retirement plan.
Where the HSA Wins
- Triple tax break. No other account is tax-free going in, growing and coming out for medical costs.
- No use-it-or-lose-it rule. Your balance rolls over and stays with you if you change jobs.
- Drawback: strict eligibility. You need a high-deductible plan, which can mean bigger bills in a bad health year.
Which One Is Right for You?
- Early-career with a match. Contribute enough to get the full match, then fund a Roth IRA.
- Healthy and HSA-eligible. After the match, max the HSA and invest it for the long run.
- High earner, 50 or older. Plan for Roth catch-ups, and check whether you hit the 60–63 window.
- Already maxing out. Raise your deferral early in 2027 so you reach the new 401(k) cap by December, then fill the IRA and HSA.
- Self-employed. Start with an IRA, then look at a solo 401(k) once income allows.
- Halal-conscious saver. Use the 401(k) for the match if a screened fund exists; otherwise lean on a halal IRA.
Key Takeaways on the 2027 401k Contribution Limit
- Next year’s 401(k) employee cap is projected at $25,500, or $25,000 if September inflation is nearly flat; the IRS confirms it in late fall.
- 2027 HSA limits are already official at $4,500 self-only and $9,000 family.
- Catch-ups grow too, with ages 60–63 projected at $11,750 extra, and high earners must make them as Roth.
- The three accounts have separate limits, so you can fund all of them in one year.
- For halal-conscious savers, the account is fine; check the funds and cash defaults inside it.
Further Reading
For a second view of the current-year numbers, see NerdWallet’s 401(k) contribution limits guide. Once the IRS publishes its notice, compare the confirmed 2027 401k contribution limit against the projections above before you change your payroll election. The official 2026 figures are in the IRS announcement.